Identity Theft Insurance Coverage Explained
You open your credit report and find a credit card you never applied for. The account has an unpaid balance, and the lender wants proof that you did not open it. You begin gathering documents, contacting credit bureaus, and disputing the debt. Then you discover that resolving the problem could involve missed work, document fees, and legal assistance.
ID theft insurance coverage helps reimburse certain expenses involved in recovering from identity theft. Depending on the policy, these may include lost wages, document replacement costs, postage, and approved attorney fees. Most standard policies do not automatically repay money stolen from your bank account, and they cannot stop criminals from accessing your personal information.
For families, the real value of an identity theft insurance plan depends on its reimbursement rules, exclusions, and claims process. A policy advertising substantial coverage might still limit the amount available for lost wages or legal fees. Before paying for protection, you need to know what the insurer will cover, who in your household qualifies, and what evidence you must provide.
What Is Identity Theft Insurance Coverage?
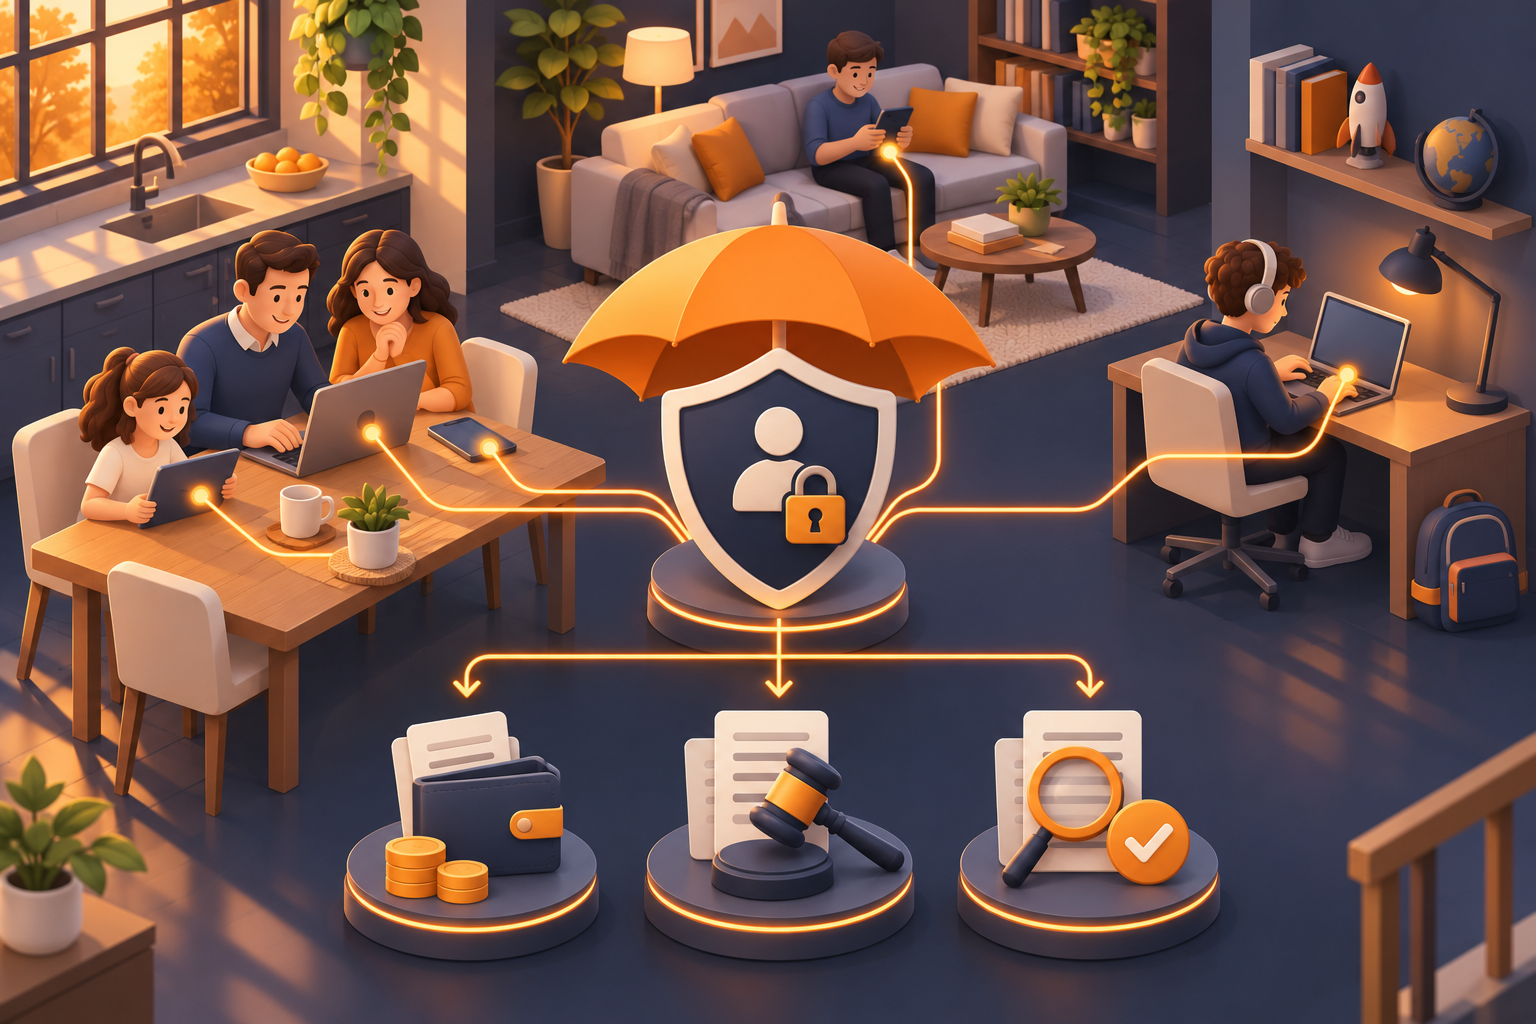
Identity Theft Insurance is a type of coverage that helps pay certain expenses incurred while repairing damage caused by identity theft.
It may be available through a standalone insurance policy, a homeowners or renters insurance endorsement, or a paid identity protection service.
The coverage generally becomes relevant after a qualifying identity theft incident occurs.
Suppose someone uses your Social Security number to open a fraudulent credit account. You discover the account, contact the lender, file disputes, and gather documents proving that the debt is not yours.
The insurer may reimburse eligible expenses associated with those recovery activities.
However, identity theft insurance does not automatically cancel the fraudulent debt, correct your credit reports, or compensate you for every hour spent resolving the problem.
Those tasks still require action through the relevant financial institutions, credit reporting agencies, or restoration service.
The Federal Trade Commission explains that identity theft insurance commonly focuses on recovery expenses rather than direct reimbursement of stolen money.
The purpose of identity theft insurance is to reduce certain financial costs of recovery, not to prevent identity theft.
That distinction should guide how you compare policies.
Common Covered Expenses in a Standard Policy
Standard identity theft insurance policies may reimburse several types of recovery expenses.
Common categories include:
- Postage for mailing fraud reports and supporting documents.
- Copying and printing costs.
- Notary fees associated with required paperwork.
- Certain replacement document expenses.
- Qualifying lost wages.
- Approved attorney fees.
- Other recovery expenses specifically listed in the policy.
Each category has its own conditions.
A policy might cover postage but require original receipts. Another might reimburse legal fees only when the insurer approves the attorney beforehand.
Do not assume that every expense arising after identity theft automatically qualifies.
Example: A fraudulent credit account
Imagine a parent discovers an unfamiliar credit card account on their credit report.
They contact the lender and dispute the account with the credit bureaus.
The lender requests an identity theft report and additional identification documents.
The parent pays for certified mail, document copies, and a notary service.
If those expenses fall within the policy’s covered categories, the insurer may reimburse them.
However, the parent must still complete the dispute process.
The insurance does not automatically remove the account from their credit history.
Example: Lost wages during identity recovery
A parent may need unpaid time off work to attend an appointment or complete a necessary identity theft recovery task.
Some policies reimburse qualifying lost wages.
The insurer may ask for employer confirmation, payroll records, or other documentation showing the amount of income actually lost.
If the parent continues receiving their normal salary, there may be no qualifying wage loss.
Self-employed individuals may face different documentation requirements.
The policy may also limit the number of reimbursable days or the total amount payable.
Before buying, check whether lost-wage coverage applies to ordinary recovery activities or only to specifically defined circumstances.
A long day spent on the telephone does not automatically mean the insurer will compensate you for that time.
Legal Fees and Case Resolution Support
Identity theft can lead to disputes that are difficult to resolve through ordinary customer service.
A fraudulent account may be transferred to a debt collector.
A creditor may continue reporting a debt after receiving a dispute.
An identity theft victim may need legal assistance to address a complicated situation.
Some policies reimburse eligible attorney fees and certain related legal expenses.
However, the insurer may require advance approval.
It may also specify which types of legal work qualify or restrict reimbursement to approved service providers.
For example, if a lender continues attempting to collect a fraudulent debt, you might consider hiring an attorney.
Before doing so, contact the insurer.
Ask whether the situation qualifies for legal expense coverage, whether the attorney needs approval, and what reimbursement limit applies.
Do not assume the insurer will repay legal fees simply because the work concerns identity theft.
Restoration Services are different from insurance reimbursement
Many identity protection packages include Restoration Services alongside insurance.
A restoration specialist may help you:
- Organize fraudulent account information.
- Prepare dispute letters.
- Contact financial institutions with your authorization.
- Understand the credit report correction process.
- Identify documents required by creditors.
- Keep track of unresolved disputes.
- Prepare supporting information for an insurance claim.
This assistance can be valuable when several accounts are affected.
For example, a person dealing with fraudulent credit cards, collection notices, and an unfamiliar loan may struggle to keep track of which institutions have responded.
A case manager can help organize that work.
However, access to a restoration specialist does not automatically mean that every expense is covered.
The restoration team may guide the recovery process while an insurance company separately decides whether a claim qualifies.
Before subscribing, ask whether the service directly contacts creditors or simply gives you instructions.
Also check whether restoration assistance is included in the monthly price or available only after a covered incident.
What an ID Theft Insurance Policy Does Not Cover
The exclusions section of an ID theft insurance policy deserves careful attention.
It explains which losses the insurer will not reimburse, even when those losses are connected to identity theft.
The biggest source of confusion is stolen money.
Many people assume identity theft insurance works like a guarantee that the insurer will replace any funds lost through fraud.
That is generally not what standard expense reimbursement coverage provides.
Direct Stolen Money and Unrecoverable Funds
Suppose someone gains unauthorized access to your bank account and transfers money elsewhere.
You discover the transaction and contact the bank.
You may expect identity theft insurance to replace the missing amount.
However, standard identity theft expense coverage generally does not reimburse money stolen directly from financial accounts.
The Federal Trade Commission and National Association of Insurance Commissioners distinguish identity restoration expense coverage from direct financial loss protection.
Some enhanced policies include separate stolen-funds benefits.
Those benefits must be specifically described in the contract.
Do not assume that a policy advertising identity theft coverage includes them.
What should you do if money disappears from your account?
Contact your bank or payment provider immediately.
Report the unauthorized activity and follow its fraud dispute procedure.
The applicable consumer protections depend on factors such as the account type, payment method, transaction circumstances, and how quickly you report the problem.
An unauthorized debit card transaction may be handled differently from a payment you personally approved after being deceived.
Your bank’s investigation is separate from an identity theft insurance claim.
Do not wait for insurance approval before reporting suspected account fraud.
Scams involving authorized transfers
Consider a message that appears to come from your bank.
The sender claims someone is attempting to steal your money and instructs you to transfer it to another account for protection.
You authorize the transfer because the message seems genuine.
The transaction may be treated differently from one initiated without your permission.
A standard identity theft insurance policy may not cover the transferred funds.
Even policies offering stolen-funds benefits may exclude certain authorized transfers.
Before buying, ask whether coverage applies to:
- Unauthorized account transfers.
- Account takeover losses.
- Fraudulent withdrawals.
- Transfers approved after an impersonation scam.
- Payment fraud involving particular account types.
These categories can have different definitions and exclusions.
A large advertised coverage limit does not answer which transactions are eligible.
Pre-Existing Fraud and Delayed Filings
Identity theft policies define when coverage begins and which incidents qualify.
Many exclude incidents that occurred before the policy’s effective date.
Some contracts also distinguish between the date identity theft happened and the date you discovered it.
For example, you might purchase coverage in November and discover in December that a criminal opened an account earlier in the year.
Whether the incident qualifies depends on the contract’s definitions and exclusions.
Do not assume that buying insurance after discovering suspicious activity will reimburse the existing problem.
Reporting deadlines can affect your claim
Insurers may require prompt notice after you discover identity theft.
They may also establish deadlines for submitting receipts and other supporting documents.
Before purchasing, find out:
- How soon you must report suspected identity theft.
- Whether claims can be started online.
- Whether an FTC Identity Theft Report is required.
- Whether certain incidents require a police report.
- Which expenses need advance approval.
- When supporting documents must be submitted.
- How the insurer handles incomplete claims.
Keep a record of when you reported the incident.
Save confirmation emails, claim numbers, and copies of submitted documents.
If the insurer requests additional information, record the request and the date you responded.
Other exclusions worth checking
Policies may exclude certain business-related losses, expenses already reimbursed by another insurer, intentional acts, or claims involving people outside the defined insured household.
Some contracts contain specific restrictions involving disputes between family members or other named circumstances.
The details vary by insurer.
Read the exclusions in the policy document rather than relying only on a benefits page.
If a term is unclear, ask the insurer to explain how it applies to a practical example.
Key Policy Limits and Hidden Exclusions to Check
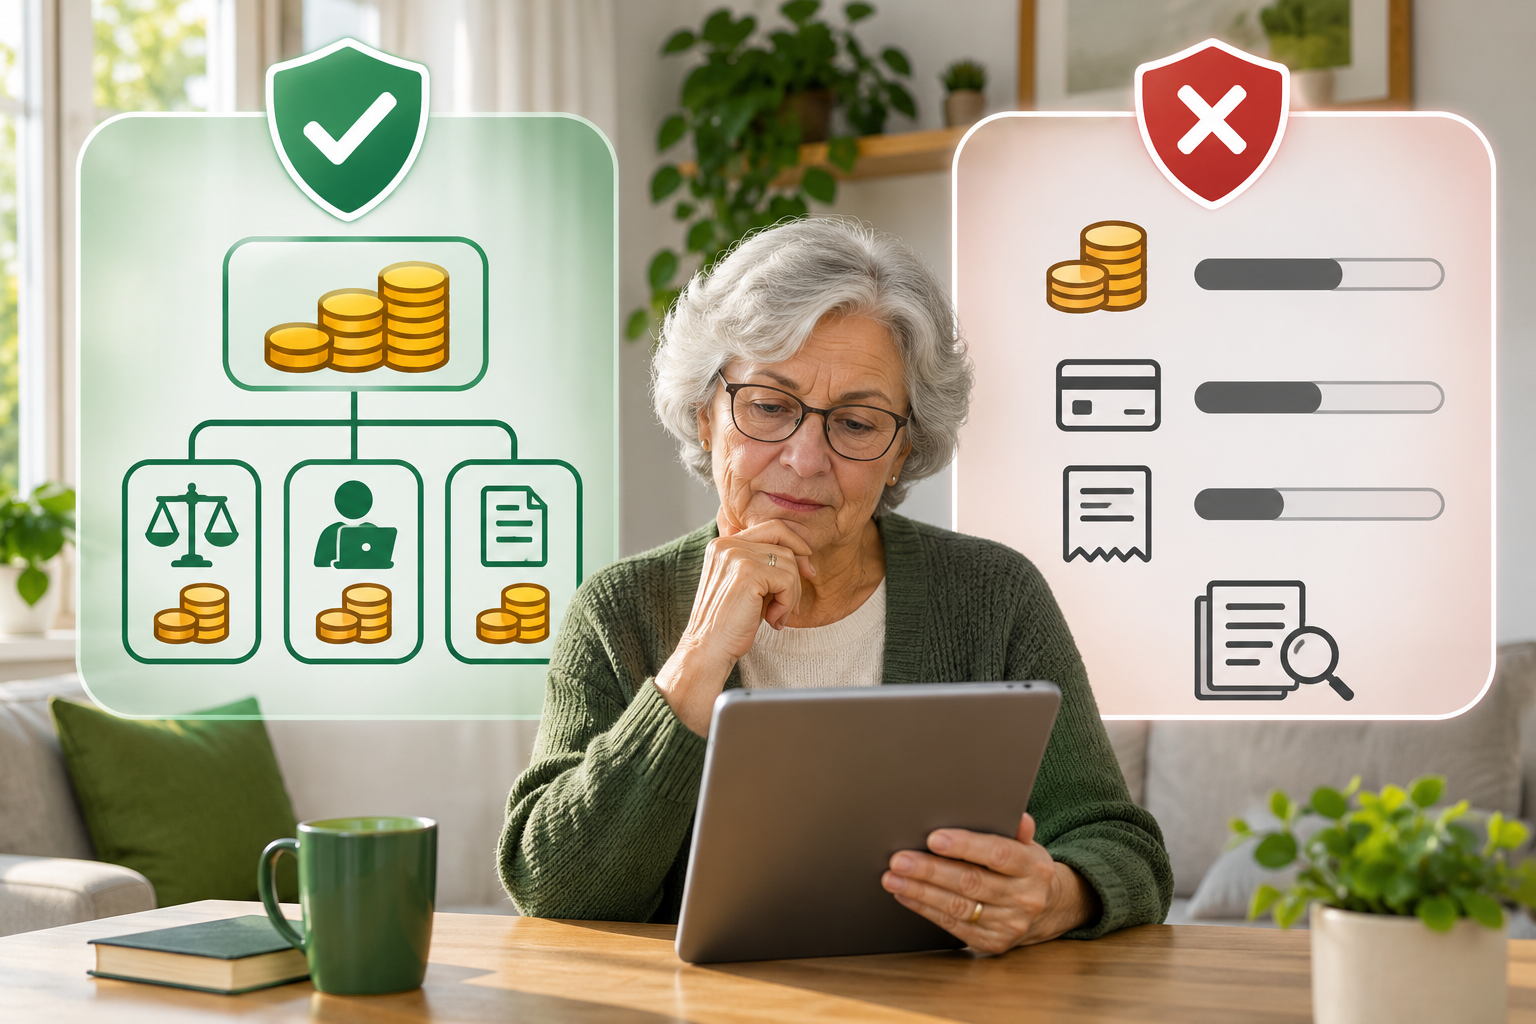
An identity theft insurance policy may advertise a substantial maximum payout.
That number does not mean the full amount is available for every claim.
Insurers may impose separate limits for lost wages, attorney fees, administrative expenses, and other categories.
A deductible may also reduce what you receive.
The most useful policy comparison looks beyond the headline amount.
Aggregate Payout Limits versus Category Caps
An aggregate limit is the maximum amount the insurer may pay under the relevant policy terms.
Depending on the contract, it may apply per incident, per person, per household, or during a policy period.
A category cap, also called a sublimit, places a smaller maximum on a particular type of expense.
For example, a policy may have a large overall identity theft coverage limit but a considerably lower limit for lost wages.
If your main concern is missing work while resolving fraudulent accounts, that smaller limit may be more relevant than the overall maximum.
Check these limits separately
- Total reimbursement limit.
- Legal expense limit.
- Lost-wage limit.
- Document replacement allowance.
- Postage and administrative expense limits.
- Stolen-funds limit, if included.
- Per-person coverage limits.
- Shared household limits.
- Limits for repeated incidents.
A family policy may provide one aggregate amount shared by several covered people.
Another may assign separate benefits to each insured member.
Do not assume either arrangement from the phrase family coverage.
Identity theft insurance comparison
| Policy feature | What to check | Why it matters |
|---|---|---|
| Aggregate limit | Whether the maximum applies per incident, person, household, or policy period | Determines the overall reimbursement ceiling |
| Legal fees | Prior approval requirements and sublimits | Unapproved attorney expenses may be excluded |
| Lost wages | Eligibility, proof requirements, and maximum reimbursement | Not every hour spent resolving fraud qualifies |
| Document expenses | Covered fees, receipts, and category limits | Common recovery costs may have restrictions |
| Stolen funds | Whether direct losses are expressly covered | Standard expense policies generally exclude these losses |
| Family coverage | Age, relationship, and residency requirements | Not every household member may qualify |
| Deductible | Amount and how often it applies | Small claims may produce little reimbursement |
| Claims deadlines | Reporting and documentation requirements | Late claims may face additional difficulties |
| Other insurance | Coordination and duplicate reimbursement rules | Existing policies can affect what is payable |
Deductibles and Proof Requirements
A deductible is the amount you must bear before an insurer reimburses eligible expenses.
Some identity theft policies have no deductible.
Others apply one per incident or claim.
The effect is easiest to understand with a simple comparison.
If your eligible recovery expenses are relatively small, a substantial deductible may absorb most of the reimbursement.
If an incident requires qualifying legal assistance or unpaid leave, the deductible may represent a smaller share of the total expense.
The contract determines the calculation.
What documents should you keep?
Identity theft claims often require evidence that an expense resulted from a covered incident.
Useful records include:
- FTC Identity Theft Report.
- Fraudulent account notices.
- Credit bureau dispute correspondence.
- Letters from lenders and collection agencies.
- Receipts for mailing, copying, and notary services.
- Approved legal invoices.
- Payroll documentation for lost wages.
- Insurance claim correspondence.
- Documents establishing a dependent’s eligibility when relevant.
Keep copies in a secure folder.
Use descriptive file names so you can identify documents without opening every file.
For example, a file name identifying the creditor, document type, and date makes a large recovery case easier to manage.
Do not send sensitive documents through an unfamiliar email address merely because someone claims to represent the insurer.
Use the insurer’s verified submission process.
If an expense is denied, ask which policy provision applies.
That helps you determine whether the problem involves missing evidence or an actual exclusion.
Insurance versus Proactive Device and Identity Protection
Insurance, identity monitoring, and device security protect against different stages of the problem.
Identity theft insurance may help with certain costs after fraud occurs.
Device security and account protection can reduce exposure to some threats before criminals obtain useful information.
Monitoring can help identify selected warning signs.
None replaces the others.
A household can have identity theft insurance and still lose access to an email account through a phishing attack.
The insurer does not block the malicious website or prevent a password from being entered.
Likewise, antivirus software cannot automatically reimburse the cost of resolving a fraudulent credit account.
Why phishing protection still matters
Phishing Attacks often begin with ordinary-looking messages.
A text may claim that a package cannot be delivered.
An email may warn that a bank account has been locked.
A fake government notice may demand immediate identity verification.
The link leads to a page designed to collect passwords, payment information, or other personal details.
Identity theft insurance does not inspect those links.
It does not prevent someone from entering information into a fraudulent website.
Phishing protection, careful link verification, and strong account authentication address a different part of the risk.
For families, email security deserves particular attention.
A compromised email account may contain financial records, tax correspondence, and password-reset messages.
If a criminal gains access, several unrelated accounts could become vulnerable.
Insurance may help with certain recovery expenses later, but it cannot replace steps that reduce the chance of compromise.
Why malware protection is different
Malware can interfere with devices, steal information, or provide criminals with unauthorized access.
An identity theft insurance policy cannot remove malicious software from a Windows laptop.
It also cannot determine whether a suspicious Android application should be installed.
Malware Protection, regular software updates, safe downloads, and appropriate device security controls address these risks.
Families comparing the best antivirus for family options should consider their actual devices and the protections supported on each operating system.
Windows, Mac, Android, and iPhone do not offer identical security capabilities.
The product features that work on one platform may behave differently on another.
A family security plan should account for those differences instead of assuming that one feature protects every device in exactly the same way.
How data breach monitoring complements insurance
Data Breach Monitoring helps identify when selected personal information appears in known data exposures.
For example, a breach alert might indicate that an email address was found in a compromised dataset.
That gives the account holder a reason to check whether the password was reused elsewhere.
They can then change affected passwords, review account activity, and enable stronger authentication where available.
However, a breach alert does not automatically mean the account was accessed.
It also cannot guarantee that every exposure has been detected.
An identity theft insurance policy does not remove information from breached databases.
If stolen information later contributes to a qualifying identity theft incident, the policy may help reimburse eligible recovery costs.
These protections have different purposes:
- Data breach monitoring: Identifies selected known exposures.
- Phishing protection: Helps reduce exposure to supported malicious links and websites.
- Malware protection: Helps protect devices against supported malicious software threats.
- Identity theft insurance: May reimburse eligible recovery expenses.
- Restoration services: May assist with correcting identity-related problems.
This distinction makes it easier to compare products without paying for overlapping features under the mistaken impression that they all perform the same function.
Protecting several family devices
A family might use a Windows laptop for tax filing, an iPhone for banking notifications, an Android phone for shopping, and a Mac for storing household documents.
Each device can contain sensitive information or provide access to important accounts.
Appropriate multi-device security software can help manage supported protections across these devices.
AVO Security provides family-oriented features including phishing protection, breach alerts, and device security.
These features can support a wider household cyber protection approach.
However, they are not a substitute for an identity theft insurance contract.
Do not assume that a security subscription includes financial reimbursement simply because it offers identity-related features.
If insurance is part of your purchasing decision, obtain the policy documents and identify the actual insurer.
Check the covered expenses, eligibility conditions, and claims process separately.
What to do immediately after identity theft
If you discover a fraudulent account or unauthorized activity, take action on the affected account first.
Do not wait for an insurance case manager before contacting the relevant institution.
- Contact the bank, lender, or service provider using its official contact information.
- Ask for the affected account to be secured, restricted, or closed as appropriate.
- Change compromised passwords and review account authentication settings.
- Report the incident to the Federal Trade Commission through IdentityTheft.gov.
- Review your reports with the three nationwide Credit Bureaus: Equifax, Experian, and TransUnion.
- Consider fraud alerts or credit freezes based on the circumstances.
- Notify your identity theft insurer and request its claims instructions.
- Save receipts, correspondence, and records of the steps taken.
The FTC provides an Identity Theft Report and a recovery plan tailored to the information you report.
An initial fraud alert can be placed through one nationwide credit bureau, which must notify the other two.
A credit freeze generally requires separate action with each bureau.
These steps can help limit further damage regardless of whether you have identity theft insurance.
How to Pick the Right Identity Theft Insurance Plan for Your Household
A suitable family policy should cover the people you intend to protect and provide meaningful assistance with expenses that could arise during identity recovery.
Do not begin with the largest advertised payout.
Begin with your existing coverage, the household members who need protection, and the types of assistance you would actually use.
Step 1: Check coverage you may already have
Before purchasing a separate policy, review your homeowners or renters insurance.
Some insurers offer identity theft expense coverage as an optional endorsement.
Others may include limited benefits in certain packages.
You may also have access to identity restoration assistance through an existing financial service or membership.
Ask for the policy documents.
Check whether the coverage includes reimbursement, restoration assistance, or both.
Do not assume two similarly named benefits offer the same protection.
If you already have appropriate coverage, another policy may add little value.
Also review how overlapping insurance is handled.
Some contracts restrict duplicate reimbursement for the same expense.
Step 2: Confirm exactly who is insured
A family subscription does not automatically mean every household member qualifies for every insurance benefit.
The policy may cover the primary subscriber, spouse, and eligible dependents.
But eligibility definitions vary.
Ask:
- Is a spouse covered automatically?
- Are domestic partners eligible?
- Are minor children included?
- What happens when a child reaches adulthood?
- Are college students living away from home covered?
- Must dependents share the policyholder’s address?
- Are benefits available separately for each covered person?
A plan may provide account monitoring for several family members while applying different conditions to insurance.
For example, a college student might remain eligible under one policy but not another.
Check the definition of an insured person rather than relying on the subscription’s marketing name.
Step 3: Compare the expenses most likely to matter
Think about what identity recovery would involve for your household.
A parent working hourly shifts may value lost-wage reimbursement.
Someone managing complicated credit disputes may care more about legal expense coverage and restoration assistance.
A household with several children may want help resolving fraudulent accounts opened using a minor’s identity.
Compare the relevant categories directly.
Do not choose a policy only because its aggregate limit is larger.
Look at the smaller limits attached to the services you expect to use.
If a policy advertises extensive insurance but provides little practical assistance with disputes, it may not meet your needs.
Step 4: Check whether stolen-funds protection is included
If your main concern is losing money through account fraud, examine the stolen-funds provisions carefully.
Standard identity theft expense coverage generally does not provide broad reimbursement of stolen account balances.
Some enhanced plans include a separate benefit.
If one is advertised, ask for its complete terms.
Check which financial accounts and transactions qualify.
Find out whether the policy distinguishes unauthorized transfers from payments approved after a scam.
Also ask whether the financial institution must complete its own investigation before the insurer considers the claim.
Do not confuse a stolen-funds benefit with reimbursement of identity recovery expenses.
They are different protections and may have different exclusions.
Step 5: Compare Restoration Services
A restoration specialist may be more useful than a large reimbursement limit for someone facing several fraudulent accounts.
But restoration services vary.
Ask what happens after you report identity theft.
Will a case manager help prepare dispute letters?
Can the service contact creditors on your behalf with authorization?
Will it help track unresolved accounts?
Does it support recovery involving a child’s identity?
Is there a dedicated contact person for complicated cases?
Some providers offer general instructions and templates.
Others may provide more involved case management.
Before paying, find out exactly what assistance is included.
A service that helps organize disputes may save time even when the insurance reimbursement is relatively small.
Step 6: Read the deductible and exclusions
Request the complete insurance contract.
Find the sections covering:
- Covered events.
- Effective dates.
- Pre-existing identity theft.
- Deductibles.
- Category sublimits.
- Household eligibility.
- Legal expense approval.
- Claim deadlines.
- Excluded losses.
- Coordination with other insurance.
Pay particular attention to incidents that occurred before coverage began.
If you have already discovered fraudulent activity, buying a new policy does not necessarily make that incident eligible for reimbursement.
Keep a copy of the policy in force when you enroll.
If terms change at renewal, the earlier version may help establish which conditions applied to a particular incident.
Step 7: Compare the complete household cost
Identity theft insurance may be sold independently or bundled with identity monitoring and restoration services.
Another option may be available through a homeowners insurance endorsement.
Compare the full recurring cost.
Check whether the price is introductory.
Find out whether the subscription renews automatically and how cancellation works.
Consider whether you are already paying for similar benefits elsewhere.
A package containing numerous features is not necessarily better value.
Focus on the benefits your household needs.
If you mainly want reimbursement for recovery expenses, a simple policy may be enough.
If you also want help managing complicated disputes, restoration services deserve more attention.
Step 8: Check the claims process before subscribing
A policy is easier to evaluate when the insurer explains how claims are handled.
Before paying, find the claims instructions.
Check whether you can report an incident online or by telephone.
Ask what documents are required for the initial notification.
Find out whether attorney fees or other expenses need approval.
Also check how claim decisions are communicated.
You should be able to identify the actual insurer, not just the company selling the identity protection package.
If a claim is denied, the contract should explain the applicable review or appeal process.
Your state insurance department can also provide information about insurance-related questions and complaints.
Step 9: Keep the policy accessible to the family
Store the insurance contract and claims information in a secure location.
Keep the insurer’s contact details with your important household records.
Make sure another appropriate adult knows where to find them.
A family should not discover during a fraud incident that only one person knows how to access the policy documents.
You do not need to share account passwords or sensitive personal records with every family member.
Instead, establish a simple way to retrieve the insurer’s instructions when necessary.
Keep renewal confirmations and changes to coverage with the contract.
That makes it easier to determine which terms apply if you need to submit a claim.
Step 10: Review the plan when family needs change
Family insurance needs change.
Children become adults.
Students move away for college.
Household members change addresses.
Financial circumstances and account usage also change.
Review the insurance policy when these changes may affect eligibility.
For example, a dependent who qualified while living at home may no longer meet the insurer’s definition after moving or reaching a particular age.
Also check changes to deductibles, coverage limits, and restoration services at renewal.
Do not assume that a policy purchased several years earlier continues providing identical benefits.
FAQ
What does an id theft insurance coverage plan actually reimburse?
An identity theft insurance plan typically reimburses eligible recovery expenses such as postage, document fees, qualifying lost wages, and approved legal costs. The amount payable depends on the policy’s limits, deductibles, exclusions, and proof requirements. Restoration services may also be included, but assistance from a case manager is separate from expense reimbursement.
Does identity theft insurance replace stolen money from bank accounts?
Standard identity theft expense insurance generally does not replace funds stolen directly from bank accounts. Some enhanced policies offer separate stolen-funds benefits, but these are subject to specific conditions and exclusions. Report suspicious or unauthorized transactions to your bank immediately rather than waiting for an insurance claim.
Is a standalone identity theft insurance policy worth the cost?
It can be worthwhile if the policy covers expenses your household would struggle to manage after identity theft and provides useful claims assistance. First, check whether similar protection is already included in homeowners or renters insurance or another existing service. Compare covered expenses, household eligibility, exclusions, deductibles, and total cost before purchasing.
How do data breach alerts complement identity theft coverages?
Data breach alerts can identify selected exposed information so you can review passwords, authentication settings, and affected accounts. Identity theft insurance addresses a different need by potentially reimbursing eligible recovery expenses after a qualifying incident. Neither replaces phishing protection, malware protection, or prompt action when suspicious account activity appears.
Identity theft insurance is most useful when you understand its limits before fraud occurs. Review who qualifies, which recovery expenses are covered, whether stolen funds are excluded, and what evidence you must submit. Keep your policy information accessible and continue protecting the family’s accounts and devices. Insurance can help pay for parts of the recovery process, but preventing account compromise and reporting suspicious activity quickly remain essential.